
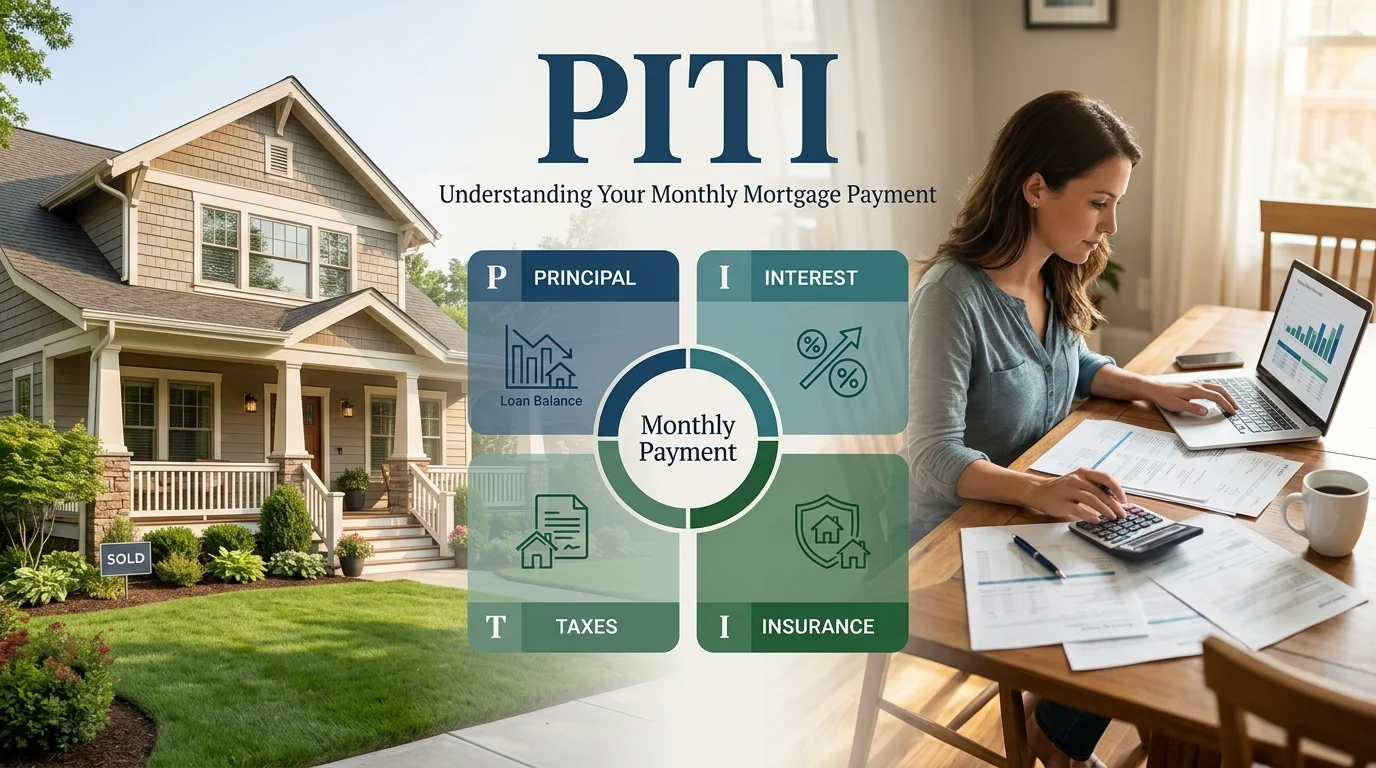
If you are shopping for a home, the advertised mortgage payment may not show your full monthly housing cost. PITI stands for principal, interest, taxes, and insurance, which make up the core of many mortgage payments. Understanding these four costs helps you compare homes and build a more realistic budget. The Consumer Financial Protection Bureau explains that an escrow account is used to collect money for property taxes and homeowners insurance and to pay those bills for the borrower. Taxes and homeowners insurance may be collected through an escrow account. Your lender then uses those funds to pay the bills when they become due.
Direct answer: The acronym means principal, interest, taxes, and insurance. Together, these costs give homebuyers a fuller estimate of a monthly mortgage payment than principal and interest alone. Taxes and insurance can change after closing, so the total payment may change even with a fixed-rate mortgage.
The Four Costs at a Glance
| Component | What It Covers | Can It Change? |
|---|---|---|
| Principal | Money used to repay the loan balance | Usually follows the loan’s amortization schedule |
| Interest | Cost charged for borrowing money | Fixed on fixed-rate loans; variable on adjustable loans |
| Taxes | Local property taxes | Yes |
| Insurance | Homeowners insurance and certain required coverage | Yes |
These four costs help buyers understand the ongoing expense of financing a property. They also help lenders evaluate whether a proposed payment fits a borrower’s finances. Other ownership costs can still sit outside this figure.
Key Takeaways
* Principal reduces the amount you owe on the mortgage. * Interest is the lender’s charge for providing the loan. * Property taxes depend on local rules and property assessments. * Homeowners insurance protects against covered losses. * Taxes and insurance are often collected through escrow. * HOA dues, utilities, repairs, and maintenance usually require separate budgeting. * A fixed interest rate does not guarantee an unchanged total monthly payment.
What Does PITI Mean in a Mortgage?
The term is an acronym used throughout the U.S. mortgage industry. The letters represent principal, interest, taxes, and insurance. Adding those expenses provides a broader payment estimate than looking only at the loan’s principal and interest. Mortgage lenders also consider housing expenses when reviewing affordability. Your expected monthly housing obligation can affect debt-to-income calculations and loan approval.
Exact underwriting requirements vary by lender, loan program, borrower, and financial profile. For more general money topics, Readella’s Finance section collects additional articles about borrowing, insurance, and household finances. Readers researching property topics can also browse the site’s Real Estate section. These resources can provide broader context around major financial decisions.
The Four Parts of a Mortgage Payment
Each component serves a different purpose. Two relate directly to the loan, while the others relate to owning and protecting the property. Understanding the difference makes mortgage estimates easier to evaluate.
Principal
Principal is the amount you borrowed to purchase the property. Each scheduled payment generally applies some money toward reducing that balance. Early payments on an amortizing mortgage often contain a smaller principal share than later payments.
Paying principal builds equity as the loan balance falls. Equity can also change when the property’s market value changes. Don’t confuse principal with the home’s purchase price, because a down payment can reduce the amount you borrow.
Interest
Interest is the price you pay the lender for borrowing money. Your interest rate, loan balance, and term affect the principal-and-interest payment. A higher rate generally increases the monthly cost for the same loan amount.
Fixed-rate mortgages keep the stated interest rate unchanged for the life of the loan. Adjustable-rate mortgages can change under the terms of the contract. Borrowers should review their Loan Estimate and loan documents before comparing offers.
Property Taxes
Property taxes are charged by local taxing authorities. The amount depends on local tax rules, assessments, exemptions, and the property itself. A tax figure from a previous owner may not always match a new buyer’s future bill. Lenders often collect one-twelfth of the estimated annual tax obligation each month. That money normally goes into an escrow account. The loan servicer then pays the property tax bill when it becomes due.
Insurance
Homeowners insurance protects the property against covered risks described in the policy. Mortgage lenders generally require suitable property insurance because the home secures the loan. Premiums vary based on location, coverage, property features, insurer, and risk factors.
Insurance costs can rise or fall after closing. Premium changes can affect the amount collected through escrow. Buyers should compare insurance estimates before deciding whether a property’s total cost fits their budget.
How to Calculate Your Full Payment
The basic calculation is straightforward once you know the required numbers. Add your monthly principal-and-interest payment to monthly property taxes and monthly homeowners insurance. You can usually divide annual taxes and insurance by 12 for a basic monthly estimate. For example, suppose principal and interest equal $1,850 each month.
Assume annual property taxes are $6,000, creating a $500 monthly estimate. If annual homeowners insurance costs $1,800, add another $150. The estimated monthly total is $2,500. That figure equals $1,850 plus $500 plus $150.
It still may not represent every expense associated with owning that home. Online mortgage calculators can speed up the math. Still, check whether a calculator includes taxes and insurance before trusting the displayed result. Some tools initially show only principal and interest.
Why Lenders Care About Your Total Housing Payment
A lender needs to determine whether the proposed mortgage fits your financial situation. Looking only at the borrowed amount would ignore major recurring ownership expenses. Taxes, insurance, and other required housing obligations can materially change affordability. Lenders commonly compare monthly debt obligations with gross monthly income.
This calculation is generally called the debt-to-income ratio, or DTI. Loan programs and lenders can apply different standards, so no single approval percentage applies to every borrower. This distinction matters when comparing mortgage advertisements.
A low principal-and-interest figure can look affordable while taxes and insurance add hundreds of dollars. Buyers should compare complete housing costs instead of focusing on one advertised number.
Does PITI Include PMI?
Private mortgage insurance, commonly called PMI, relates to mortgages but often causes confusion. The traditional acronym itself contains only principal, interest, taxes, and insurance. Some payment estimates may show mortgage insurance as an additional required monthly charge. PMI commonly applies to certain conventional mortgages when the borrower has limited equity.
Whether you need it depends on the loan and your circumstances. Your Loan Estimate should show projected mortgage insurance when applicable. Treat PMI as part of your practical housing budget even when a calculator separates it. Leaving it out can make a property appear cheaper than it will be each month. Your lender can confirm exactly how the charge appears in your payment.
Are HOA Fees Part of the Payment?
Homeowners association dues are not one of the four standard components. You normally pay them separately to an association. Lenders may still consider required HOA dues when assessing your overall housing obligations. That means a $2,500 mortgage estimate could understate your real monthly cost. A $300 HOA assessment would bring the combined housing outflow to at least $2,800 before utilities and maintenance.
Special assessments could create additional expenses. Always ask whether a property belongs to an association before making an offer. Review current dues and available association documents during your buying process. Condo buyers should pay particular attention because association costs can form a substantial monthly expense.
What Costs Are Not Included?
A mortgage payment is only one part of homeownership. Utilities, repairs, maintenance, renovations, and association fees may sit outside the lender’s monthly collection. Closing costs are also separate because they generally occur around the purchase transaction. Home condition can materially affect future spending. For example, roof condition can influence repair planning and insurance decisions.
Readella’s guide to roof appraisal costs explains several factors that can affect evaluation expenses. Buyers should therefore maintain a housing budget beyond the lender’s required payment. A repair reserve can help absorb unexpected costs after moving in. The right amount depends on the property’s age, condition, and your finances.
Why Can Your Mortgage Payment Change?
A fixed-rate mortgage does not necessarily mean your total payment stays identical forever. Principal and interest normally remain predictable on a standard fixed-rate loan. Property taxes and homeowners insurance can still change. If either expense rises, your servicer may need to collect more through escrow. An escrow shortage can also affect future monthly collections.
Your servicer generally provides information explaining changes after an escrow review. This is why buyers should leave room in their monthly budget. Using every available dollar for the initial payment can make future increases harder to manage. A comfortable payment provides more flexibility for taxes, insurance, repairs, and other expenses.
How to Estimate Your Real Monthly Housing Cost
Start with the complete mortgage payment shown in your loan documents. Then add any expenses that the lender does not collect for you. This approach gives you a more useful number for household budgeting. Consider these costs:
* Mortgage principal and interest * Property taxes * Homeowners insurance * Mortgage insurance when required * HOA or condo dues * Utilities * Routine maintenance * Expected repairs * Special assessments when applicable
Compare that total with your existing household expenses and savings goals. Do not rely only on the maximum amount a lender says you can borrow. A loan can meet underwriting requirements without matching your preferred lifestyle or financial priorities.
P&I vs. PITI: Why the Difference Matters
Principal and interest, often written as P&I, describe only the loan repayment portion. The broader mortgage figure adds property taxes and insurance. That difference can substantially affect the payment a buyer should expect. Suppose an online advertisement shows $1,900 monthly for principal and interest.
Adding $550 in taxes and $175 in insurance would raise the estimate to $2,625. HOA dues or mortgage insurance could push the practical housing cost higher. Ask what is included whenever you see a monthly payment in a listing, advertisement, or calculator. Comparing complete figures creates a fairer comparison between properties. It can also prevent an unpleasant surprise during underwriting.
Frequently Asked Questions
What does PITI stand for?
PITI stands for principal, interest, taxes, and insurance. These are four major costs commonly associated with a monthly mortgage payment. Principal and interest relate to the loan, while taxes and insurance relate to property ownership and protection.
Is escrow the same thing as a full mortgage payment?
No, escrow is an account that holds money for certain bills. Lenders often collect estimated property taxes and insurance through this account. The servicer later pays those bills using the escrowed funds.
Can my payment rise with a fixed-rate mortgage?
Yes, because a fixed rate normally applies to the loan’s interest rate. Property taxes and insurance premiums can still increase. Higher escrow requirements can therefore raise your total monthly payment.
Are utilities included in my mortgage payment?
Utilities are generally separate household expenses. Electricity, water, gas, internet, and similar services normally require direct payment to their providers. Include them when calculating your realistic monthly housing budget.
Should I use the lender’s maximum approval amount as my budget?
Not automatically. Approval reflects underwriting standards, not every personal spending goal. Your own budget should account for savings, repairs, lifestyle costs, and financial emergencies.
The Bottom Line for Homebuyers
Understanding the complete mortgage payment makes home shopping more realistic. Principal and interest matter, but taxes and insurance can change the affordability picture. Additional costs such as HOA dues and repairs also deserve space in your budget.
Before making an offer, compare the lender’s projected payment with the property’s likely ownership costs. Review your Loan Estimate and ask which expenses are included in the quoted figure. A complete estimate helps you choose a home that works after closing, not only on approval day. —
